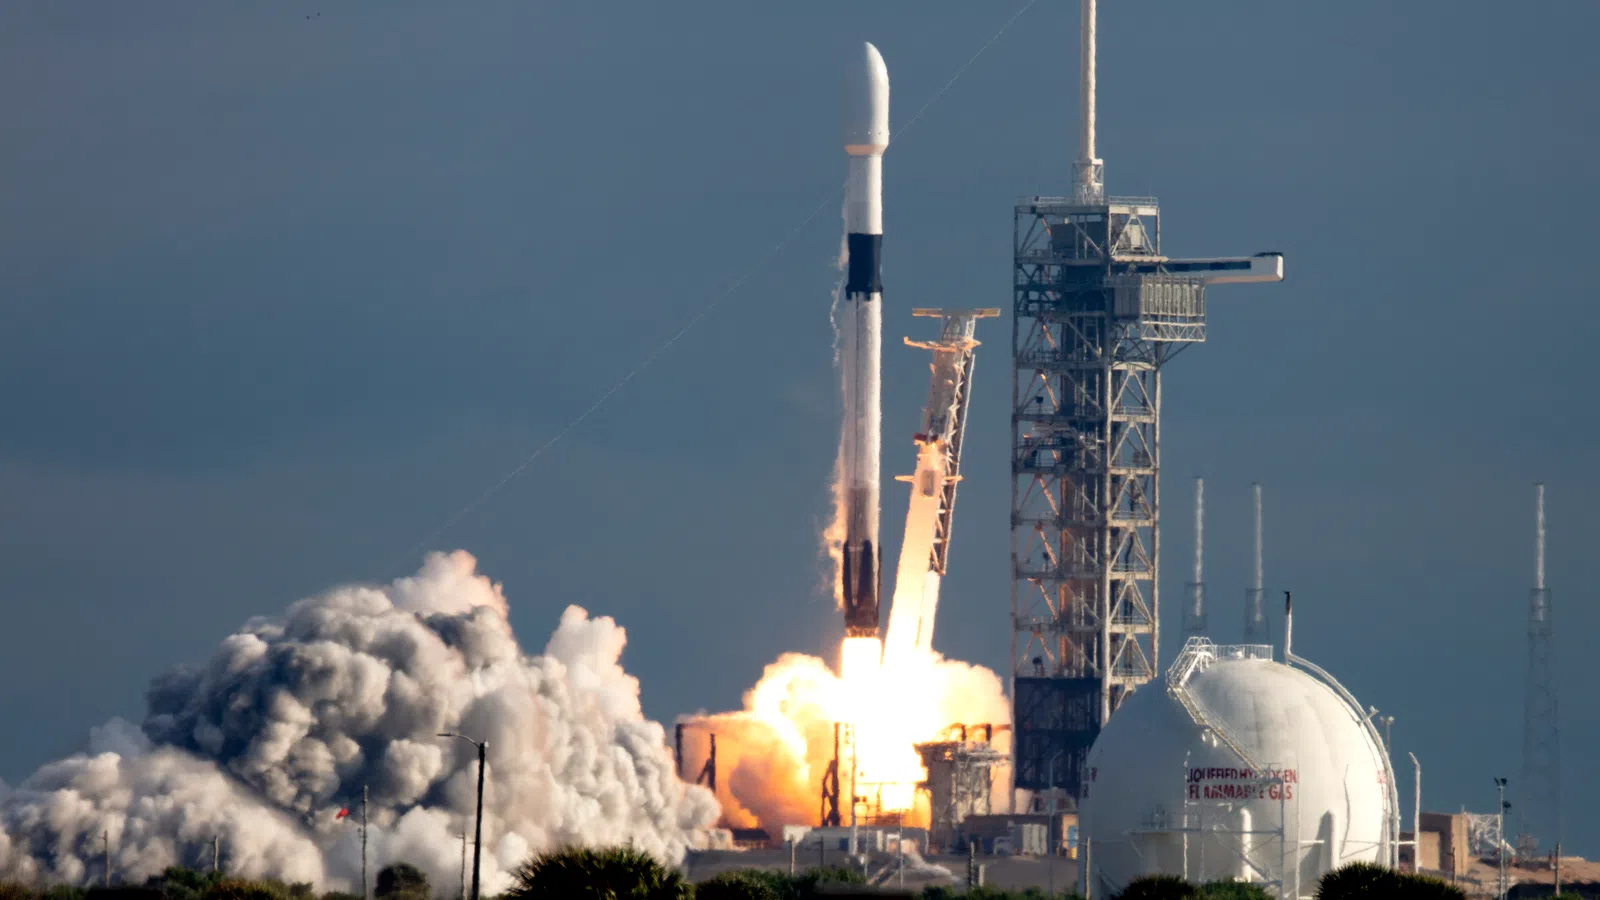
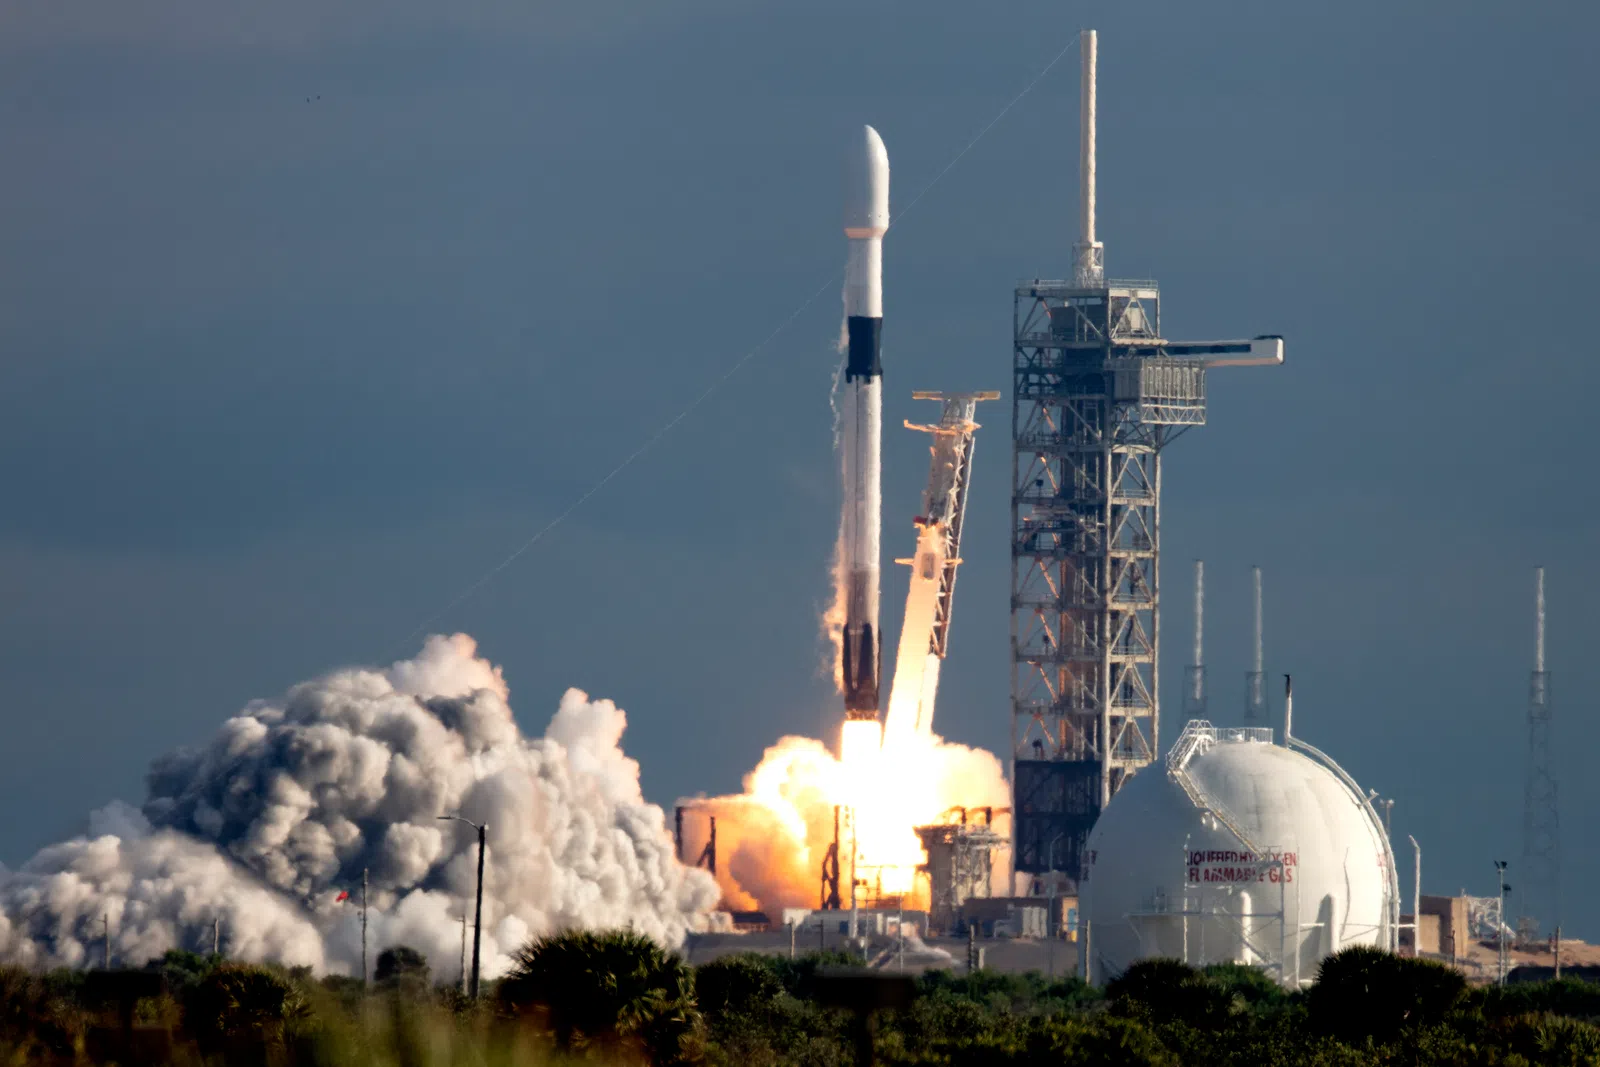
The report below gives a good overview of the Fall 2026 M&A activity in the Aerospace, Defense & Government Industry Sector. The global aerospace, defense and space sectors entered late Q3 2026 with unprecedented demand, record backlogs and mounting pressure to accelerate production and deliveries. In 2025, the 100 largest aerospace and defense companies earned more than $1 trillion in combined revenue for the first time, as did the value of commercial aircraft order books. With nearly 17,000 aircraft on order, equal to almost ten years of production, the industry's focus has shifted from winning new orders to building aircraft. Airlines are keeping older jets in service to cover delivery delays, which lifted global maintenance, repair and overhaul (MRO) demand to $136 billion in 2025, with spending expected to approach $193 billion by 2030. Space is becoming core commercial and national security infrastructure, with the global space economy growing 12% to a record $686 billion in 2025. Advanced air mobility is moving from flight testing toward commercial service, with its market projected to grow from $17.2 billion in 2026 to $128.2 billion by 2035. On the defense side, conflict and depleted stockpiles have lifted defense backlogs by more than 50% over three years, and Washington has invoked the Defense Production Act, which lets it coordinate manufacturers directly, to rebuild munitions stocks. The House authorized $1.15 trillion for national defense in fiscal 2027, Japan requested a record $55.6 billion for defense and European allies and Canada are set to spend about $634 billion in 2026. Tariffs on alloys and microelectronics, long lead times for castings and forgings and shortages of engineering talent still cap output, so production execution rather than demand will decide industry growth.
Posted by Jim Gerberman.
Read the Entire Fall 2026 Aerospace, Defense & Government Report Here